Death and Property

Earlier this year, my father became very sick and died after about six weeks in the hospital. Dealing with my father's affairs gave me a perspective I didn't have before, not just emotionally, but practically: I suddenly found myself dealing with property, financial accounts, personal belongings, paperwork, insurance, utilities, maintenance, and decisions about what happens next, while also trying to process my grief. It was a tall order and I don’t wish my experience on anyone…but chances are that you will go through the loss of a family member at some point, and you might wish you’d read this to help you avoid some of the inevitable confusion and stress.

  • Please, for the sake of everyone you care about, make a will. Feeling like what you have to leave behind isn’t worth the effort? Turns out that not having a will can require even more effort from your closest relative since they’ll be responsible for hiring an attorney to sort out everything with the probate court. And remember to update your will during significant life changes like marriage, buying a home, having children, divorce, etc. A basic will shouldn’t cost much to have prepared and (this is important) recorded with the county, so be an adult and get it done.

  • Discuss your parents’ plans and wishes with them now; don’t wait for them to bring it up. Knowing what documents we would need and where they were kept was a challenge. Dad kept everything, but wasn’t the most organized and had just moved to a new home last year. I went through 20 boxes of paperwork and several years of emails to piece together where his banking, credit & investment accounts were, which bills were on auto-pay, who handled taxes and insurance, what military and government records we needed for his federal pension, and even proof of when his 5 marriages and 4 divorces took place. To compound matters, my stepmother had let dad handle all of the finances while she handled their businesses, and they had never discussed most of these details or shared logins for account websites. This is a true benefit of those password management programs — make sure someone you trust has access to it!

  • Learn all you can about all the real estate & the personal property within it. How real estate is owned can vary; in some states, your surviving spouse has ownership rights to a certain percentage of your primary residence by virtue of your marriage, but in other cases it is less clear. Know how each property is titled on the deed and whether there is a transfer on death affidavit, will, or trust. Luckily my dad’s new condo was already paid off with the proceeds from their previous home, but there are still property taxes, HOA fees, and utilities that needed to be transferred into the trust’s name (or my stepmom’s name when necessary) and added to her monthly budget.

  • Get professional help when selling an estate property. A real estate agent can help you determine the current value of the home, what kinds of repairs might need to be made, and provide feedback on other improvements that could increase the resale value. They can also help mediate potentially emotional discussions about which improvements are worth doing, who pays for them, and how they are reimbursed. They’ll help ask the most practical questions, like “What condition is it in? What needs to be done? What are the carrying costs? What does the market look like? What would it realistically sell for as-is?” Your agent can also connect you with great local resources to help with selling and donating personal items, cleaning, renovations, and more. HOWEVER…an attorney can help you determine who has the right and/or obligation to sell the property, so make sure you’re consulting one during this process.
Inspection Issues & Solutions

As an agent, I’ve attended hundreds of inspections and read through so many inspection reports —whole house, wood destroying insect, sewer scope, structural engineering, septic, you name it! All buyers have different different standards when it comes to issues that arise during home inspections, but almost all of them have the same questions. Does the seller have to fix that? How big of a deal is that? Would you buy this house?

One important thing to consider is that a seller is never obligated to bring a property up to current code (unless it’s new construction or an occupancy permit is pending), and they don’t need to agree to do any repairs before closing. True, refusing to make any repairs can make it difficult for a seller to find a buyer for their property, but they might opt to offer a credit at closing or payments to contractors instead of handling the repairs themselves for a variety of reasons. Not agreeing to repairs doesn’t necessarily mean that a seller is being difficult; some sellers are unable to afford repairs or they are simply afraid that a buyer could still walk even after they’ve sunk the money for repairs.

My top concerns

I always start by checking for major mechanical defects; in fact, those are really the only issues that most buyers and sellers in my area are supposed to be concerned with during the inspection contingency of the contract. I want to know the condition of the exterior of the home, including the roof, windows, doors, and foundation. Is the roof old? You might want to talk to your insurance agent about how that will affect its insurability. Are the windows original, single-paned, and barely operable? Let’s find out how that’s affecting the average monthly utility bill. Cracks in the foundation? Let’s get an expert to tell us how serious that is, how to fix it, and think about how the next buyer will feel about the issue when it’s your turn to sell.

Next, I’m interested in the major systems of the home: HVAC, electrical, plumbing, & sewer. Was it possible to test both heating and cooling, and did they function equally throughout the home? Does the electrical panel look like it was wired by a 9 year old or a pro? Is the hot water taking 15 minutes to get to the shower upstairs? Any roots or breaks in those sewer lines? All of these issues could lead to major expenses down the road, so it’s important to check as thoroughly as possible.

For some buyers, there are other issues that could prevent financing via FHA, VA, or USDA. Even though these wouldn’t normally be considered “major mechanical defects,” we have to consider these as important if you want to move forward with the purchase. Appraisers have a whole list of items to check on for these loan types, but the most common ones I see are missing or non-working GFCI outlets (these should usually be anywhere within 6’ of a water source, the garage, and exterior outlets). Missing handrails on stairs, peeling paint, lack of attic insulation, and deck railings that don’t meet code come up fairly often as well.

Specialized inspections and issues

It’s always a great idea to have a home inspected for wood destroying insects (WDI), which include termites, carpenter bees, and a host of other insects that can cause significant damage to a home over time without treatment. While sellers in Ohio and Kentucky are not required to pay for treatment, it’s a common and reasonable request since most buyers would prefer that any potential damage be minimized sooner rather than later.

Radon inspections have become quite common in our area, thanks to an abundance of this naturally occurring gas in our soil. The test involves taking hourly readings of radon content in the air over the course of two or three days, and mitigation (recommended only if the average reading is above EPA guidelines) involves installing a ventilation system to carry the gas to the exterior of the home where it can be dispersed into the air. Since prolonged exposure to radon gas has been linked to various forms of cancer, it’s not unreasonable to ask a seller to cover the cost of installing a mitigation system, but I have seen several cases of a seller pushing back, either because they don’t agree that radon is a serious issue or because the level was so close to the EPA limit that the test could have been flawed.

Weird, Unusual, & Unfortunate

Most of the time, I can prepare my buyers and sellers in advance for potential inspection issues and both parties are able to come to an agreement. But sometimes there are surprises during inspections that cause a buyer to walk away, or a seller refuses to cover an expense that a buyer simply can’t afford. Here are a few examples over the years of issues that I definitely thought would tank a deal (and sometimes they did):

  • The sewer scope revealed a serious break in the sewer line between the house and the sewer main, and the estimate to fix it was over $30,000.

  • A septic inspection revealed that while the system had been passed by the county multiple times, it was in fact discharging into a nearby creek which meant an entirely new system needed to be installed at a cost of around $40,000.

  • An attic was covered in mold due to a small but ongoing leak and a lack of ventilation, and remediation was estimated at $10,000.

  • A home had been wired with aluminum wiring, which is no longer used due to fire safety concerns; remediating every outlet, switch, and fixture cost around $6,000.

  • The rear wall of a home was riddled with termites and termite damage, requiring complete reconstruction at a cost of about $20,000.

Would it surprise you to learn that only ONE of these issues resulted in a cancelled contract? It’s an important reminder that many contracts fall apart during inspections for much smaller issues, because each situation has its own complexities, but if both parties are committed to the same goal it is often possible to find a way through any situation. Be sure to discuss any concerns with your inspector, your agent, and any other experts to make sure you know how you’d like to handle inspection issues and negotiations.

The Best Time to Buy and Sell a Home

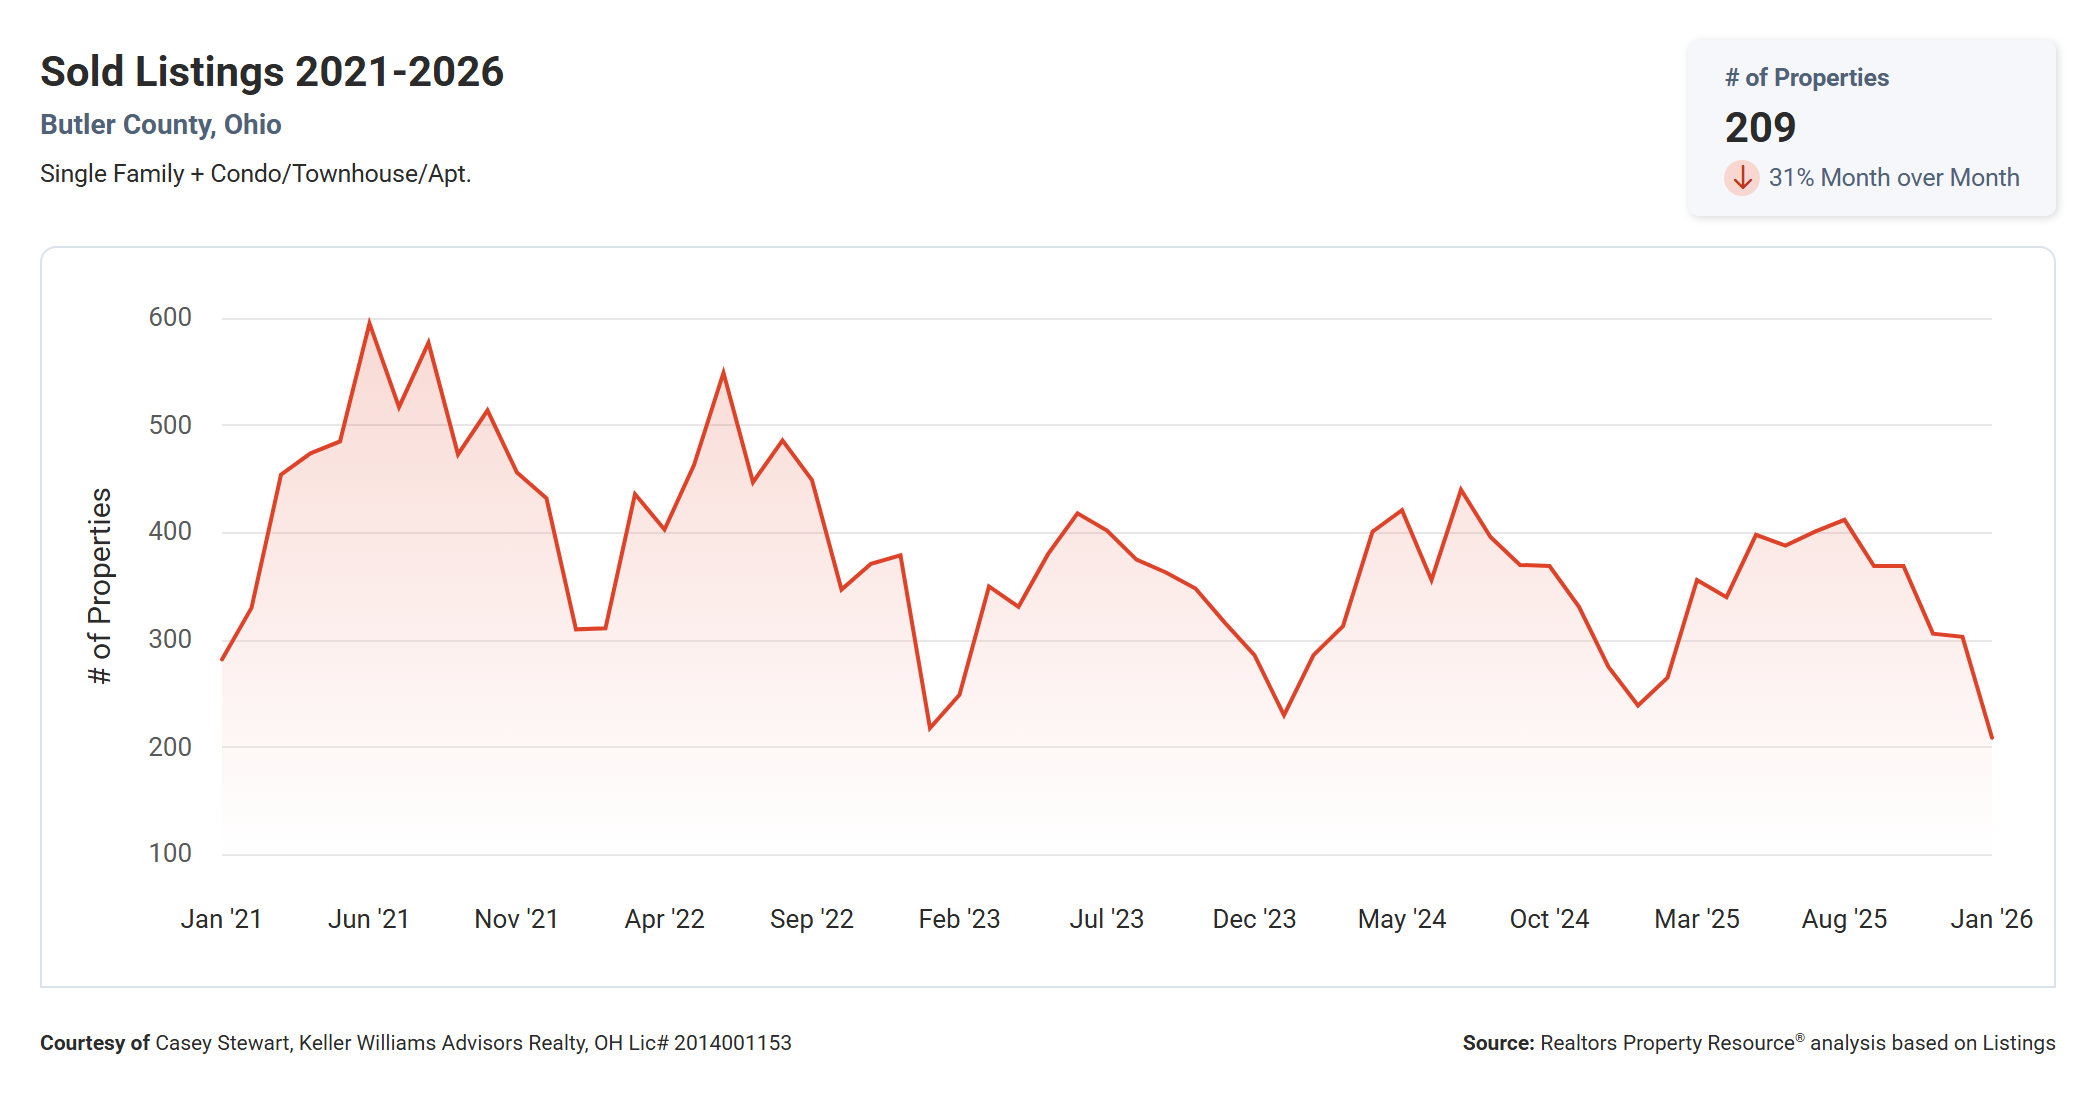
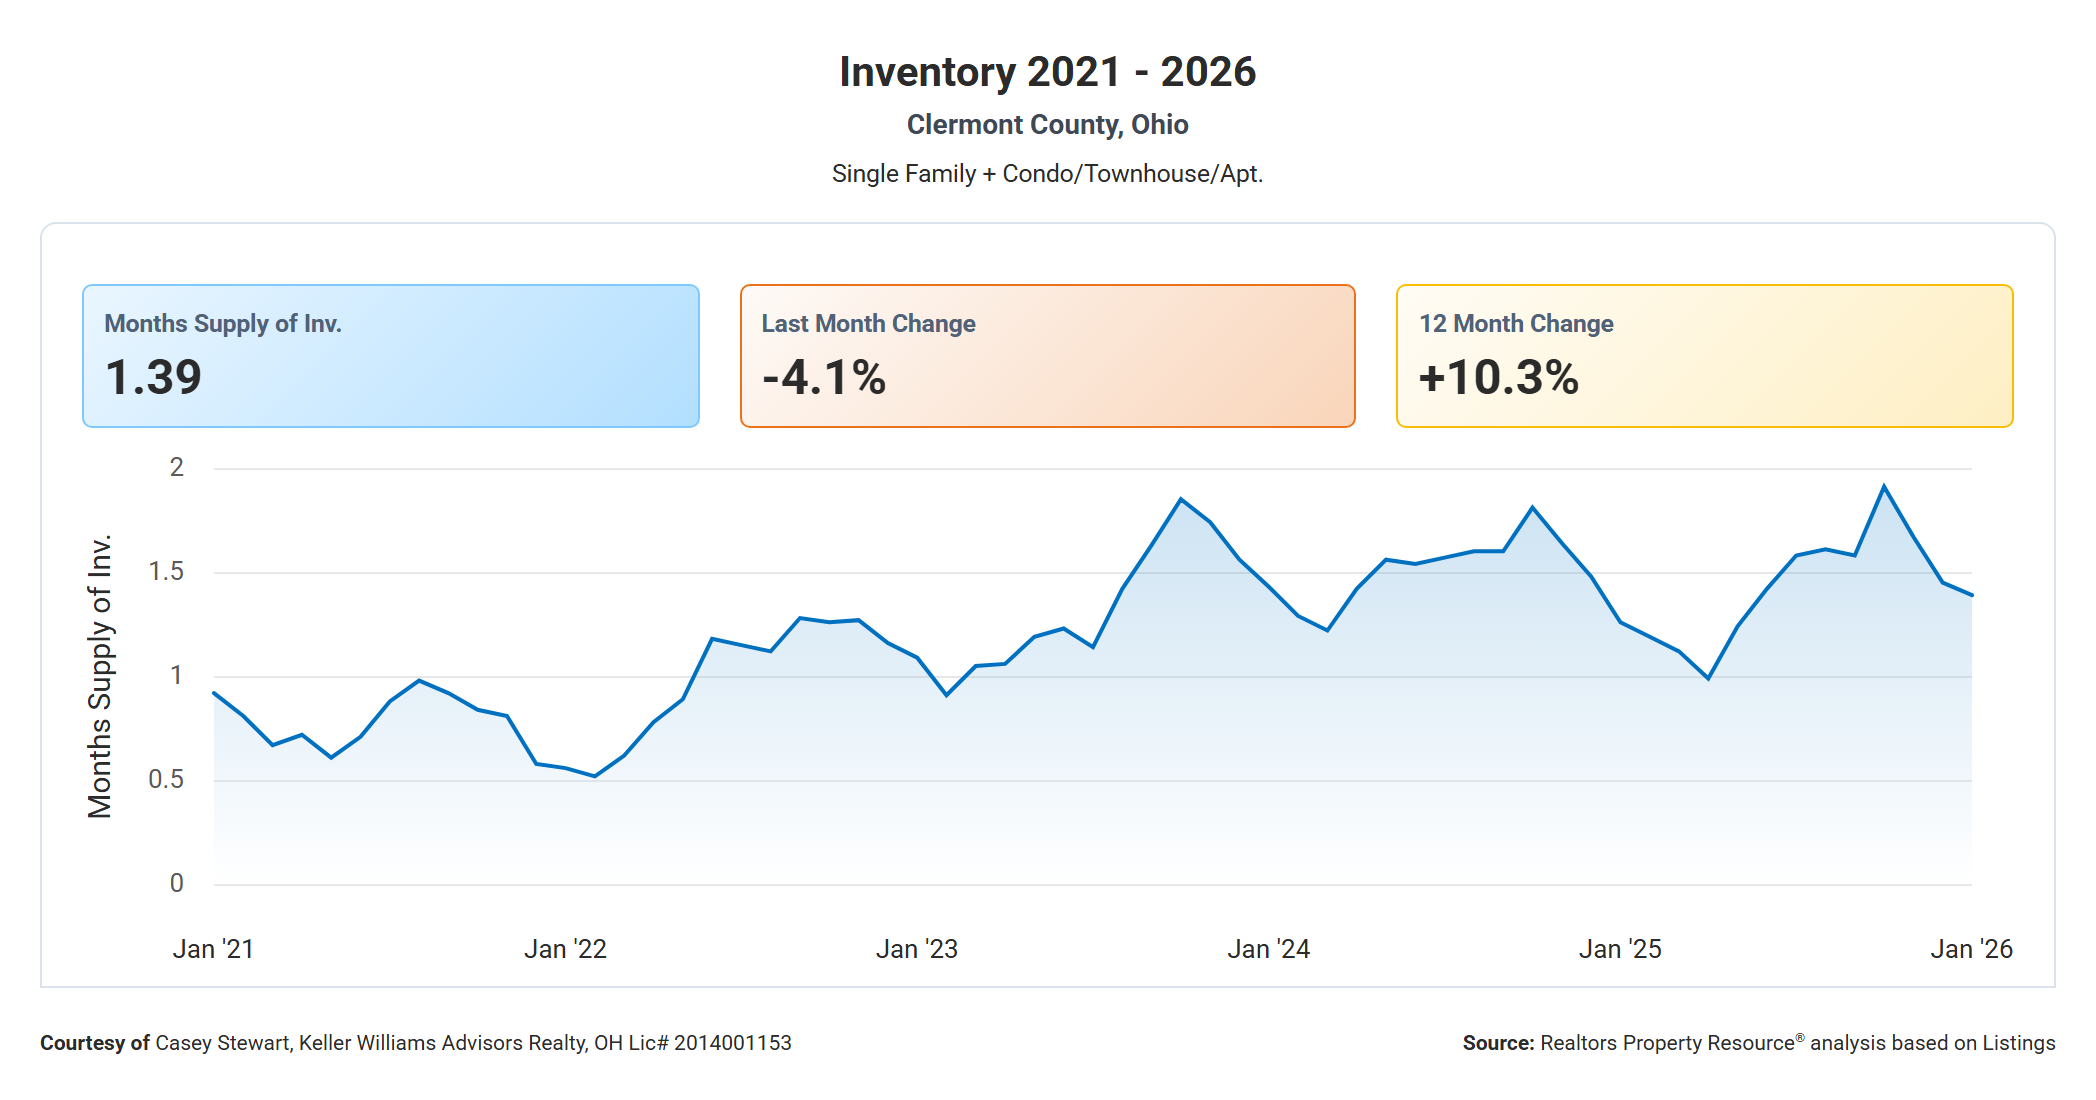
Have you ever heard that Spring is the best time to sell a home? While there are certainly seasonal patterns in the greater Cincinnati real estate market just like most places, the main thing to consider is what the situation is when you are ready to sell or buy. Timing does matter, but having a good strategy for the season you’re in matters more!

March to May: More Inventory, More Competition

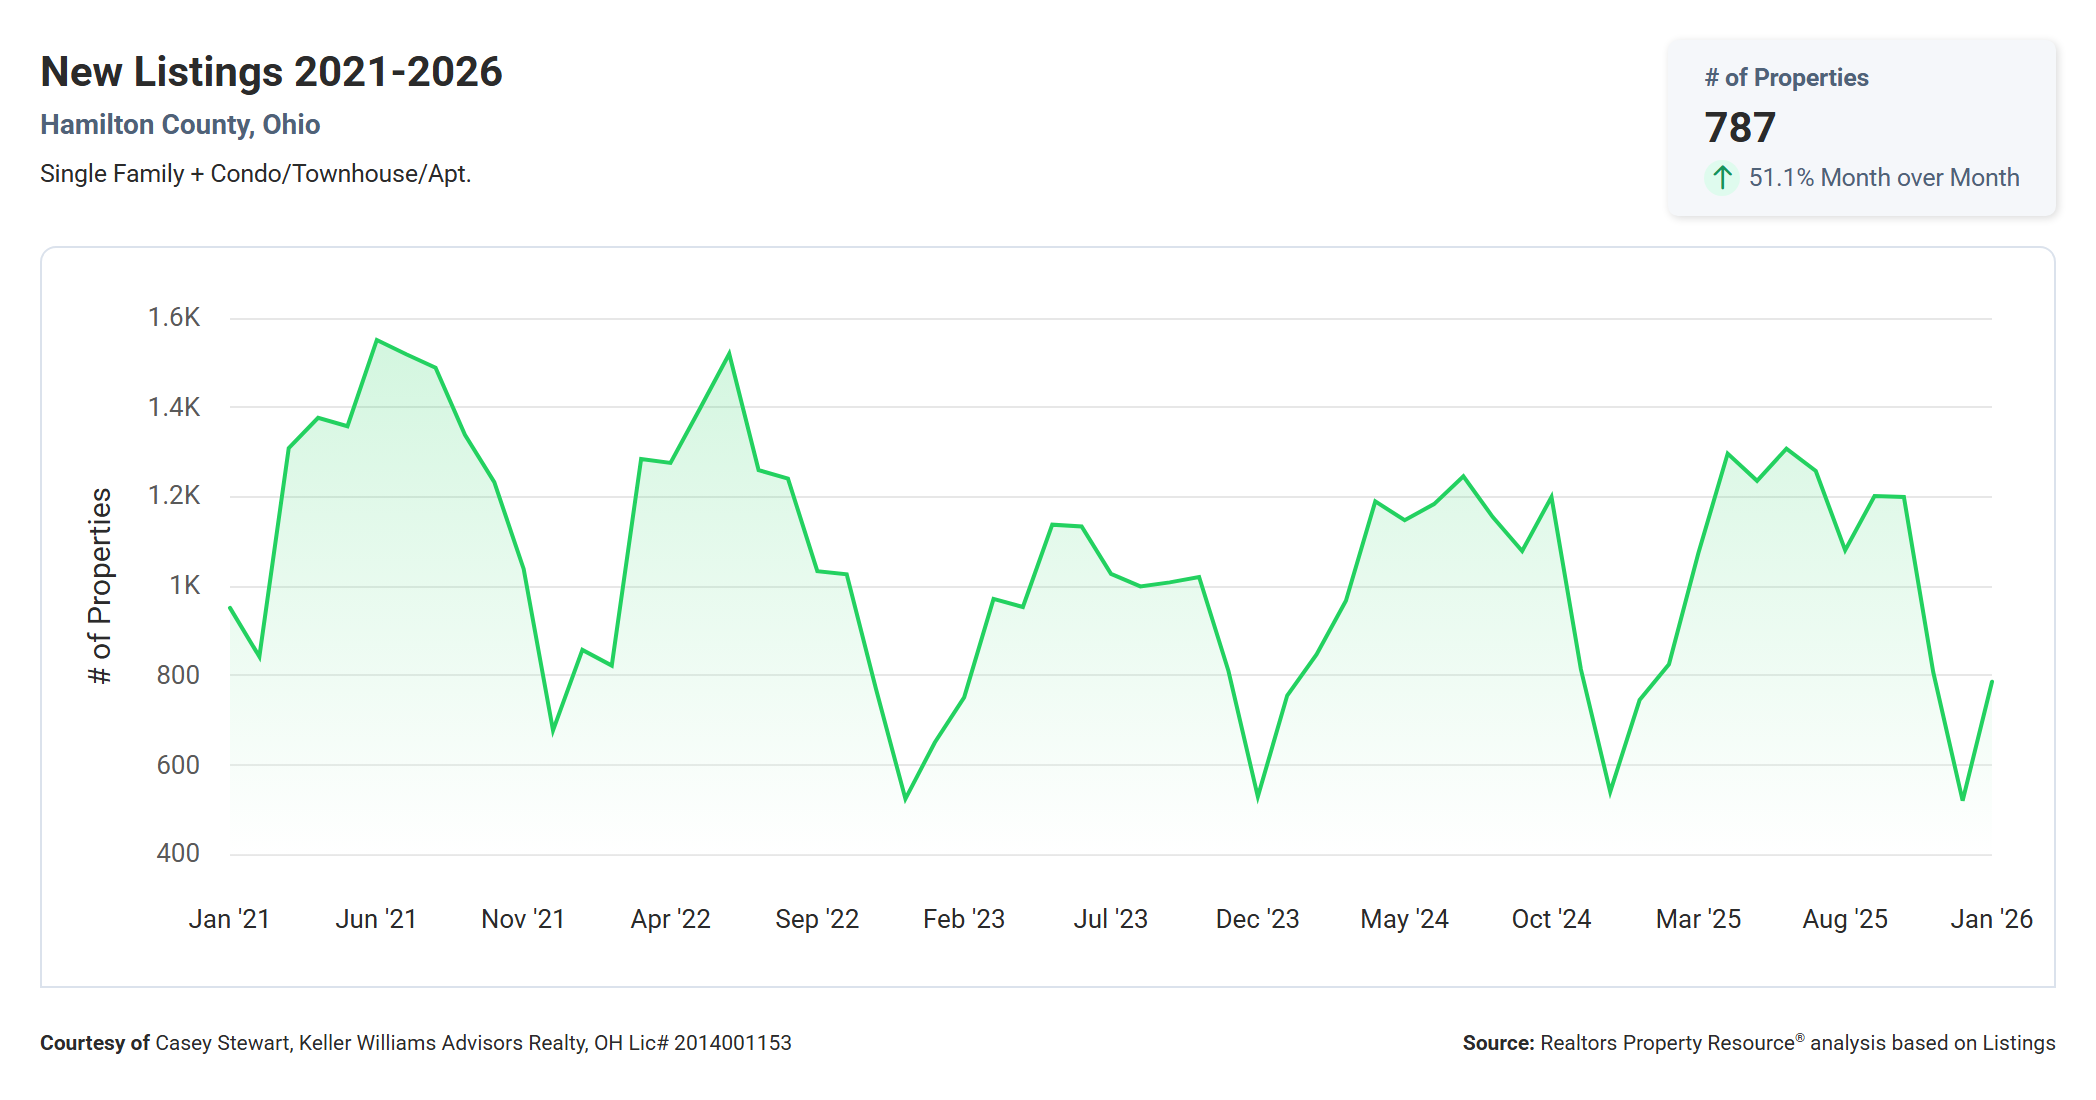
Line graph showing number of new listings by month in Hamilton County, OH between January 2021 and January 2026

Due in part to school calendars, better weather, and corporate relocations, Spring is still the most popular time of year to see new homes come up for sale. You’ll see this pattern most dramatically in high demand school districts, because many families find it easier to make a move when their children are out of school for the summer. For sellers, this can mean that you are competing against more listings, so it can be tough to stand out; you’ll want a solid agent advising you on pricing, presentation, and negotiations to make sure you achieve your goals.

Buyers know this pattern if they’ve been watching the market for a little while, and they know it will mean more options to choose from, but also multiple offer situations due to the large number of competing buyers this time of year. Without strong financing and expert negotiation, it can be tough to win and many Spring shoppers find themselves having to write a few offers before they get under contract. Buyers who need concessions from sellers often have trouble competing in the Spring, but if they’re willing to take on a home that might need some updating or has other issues that their competitors turn down, deals can still be made!

June to August: Still Active, More Pressure

As schools start to close for the summer, there are usually still plenty of homes on the market, but this starts to change over the summer. Many buyers start to feel that they’re under more pressure to find the right home before school starts up again, and sellers start to worry that they’ll run out of time as well while watching other homes go pending. Plus, many families choose summer for their family vacations, so between being out of town and coordinating summer sports activities, it can be more challenging to get to the right house at the right time.

On the upside, most homes show their best in the summer! Sellers should focus more than ever on their curb appeal and landscaping during this time. Buyers normally see a little less competition by this point in the year, and they often have a little more time to make a decision. This can mean more contracts staying together than during busier times.

September to November: More Opportunities

Autumn traditionally brings fewer new listings to the market, and homes tend to stay on the market longer which usually results in more price reductions than other seasons. Sellers during this time are usually more motivated, and since some Buyers have decided to hold off until the next year by this point, Buyers should see less competition overall. This particularly benefits move-up Buyers who need to sell their current home in order to buy the next one, property investors who can more easily pick out the homes that aren’t appealing in their current state to the rest of the buyer pool, and first time buyers who might not have been as attractive to sellers earlier in the year.

December to February: Less Volume, More Intent

If there’s one rule about winter, it’s that anyone who’s buying or selling during this time is likely to be very motivated. There’s less daylight to see homes, colder temperatures, and lots of holiday activities to juggle on the calendar. Most homes don’t look as pretty without leaves on the trees, and snow is only charming to a point. Sellers can expect serious buyers during the winter who really want or need to move, perhaps due to hating their rental, job relocation, or other life events. Buyers won’t have as much competition in the marketplace, but they’ll also have less to choose from so it’s not the ideal season to be picky.

Winter is a great time to reach out to your agent, though, if you are considering making a move in the next 12 months. Sellers will have more time to get an idea of their home’s current and projected resale value, professional input on what improvements might be worth the money, and which season might be best for their particular neighborhood and situation. Buyers can start casually viewing homes for sale, and first timers especially can use this time as a learning period to see what types of homes they might like, what some common areas of concern might be, and which homes sell faster than others — while at the same time continuing to save for their down payment, or improving their credit to put themselves in a better position when they find the right home.

Should You Time the Market?

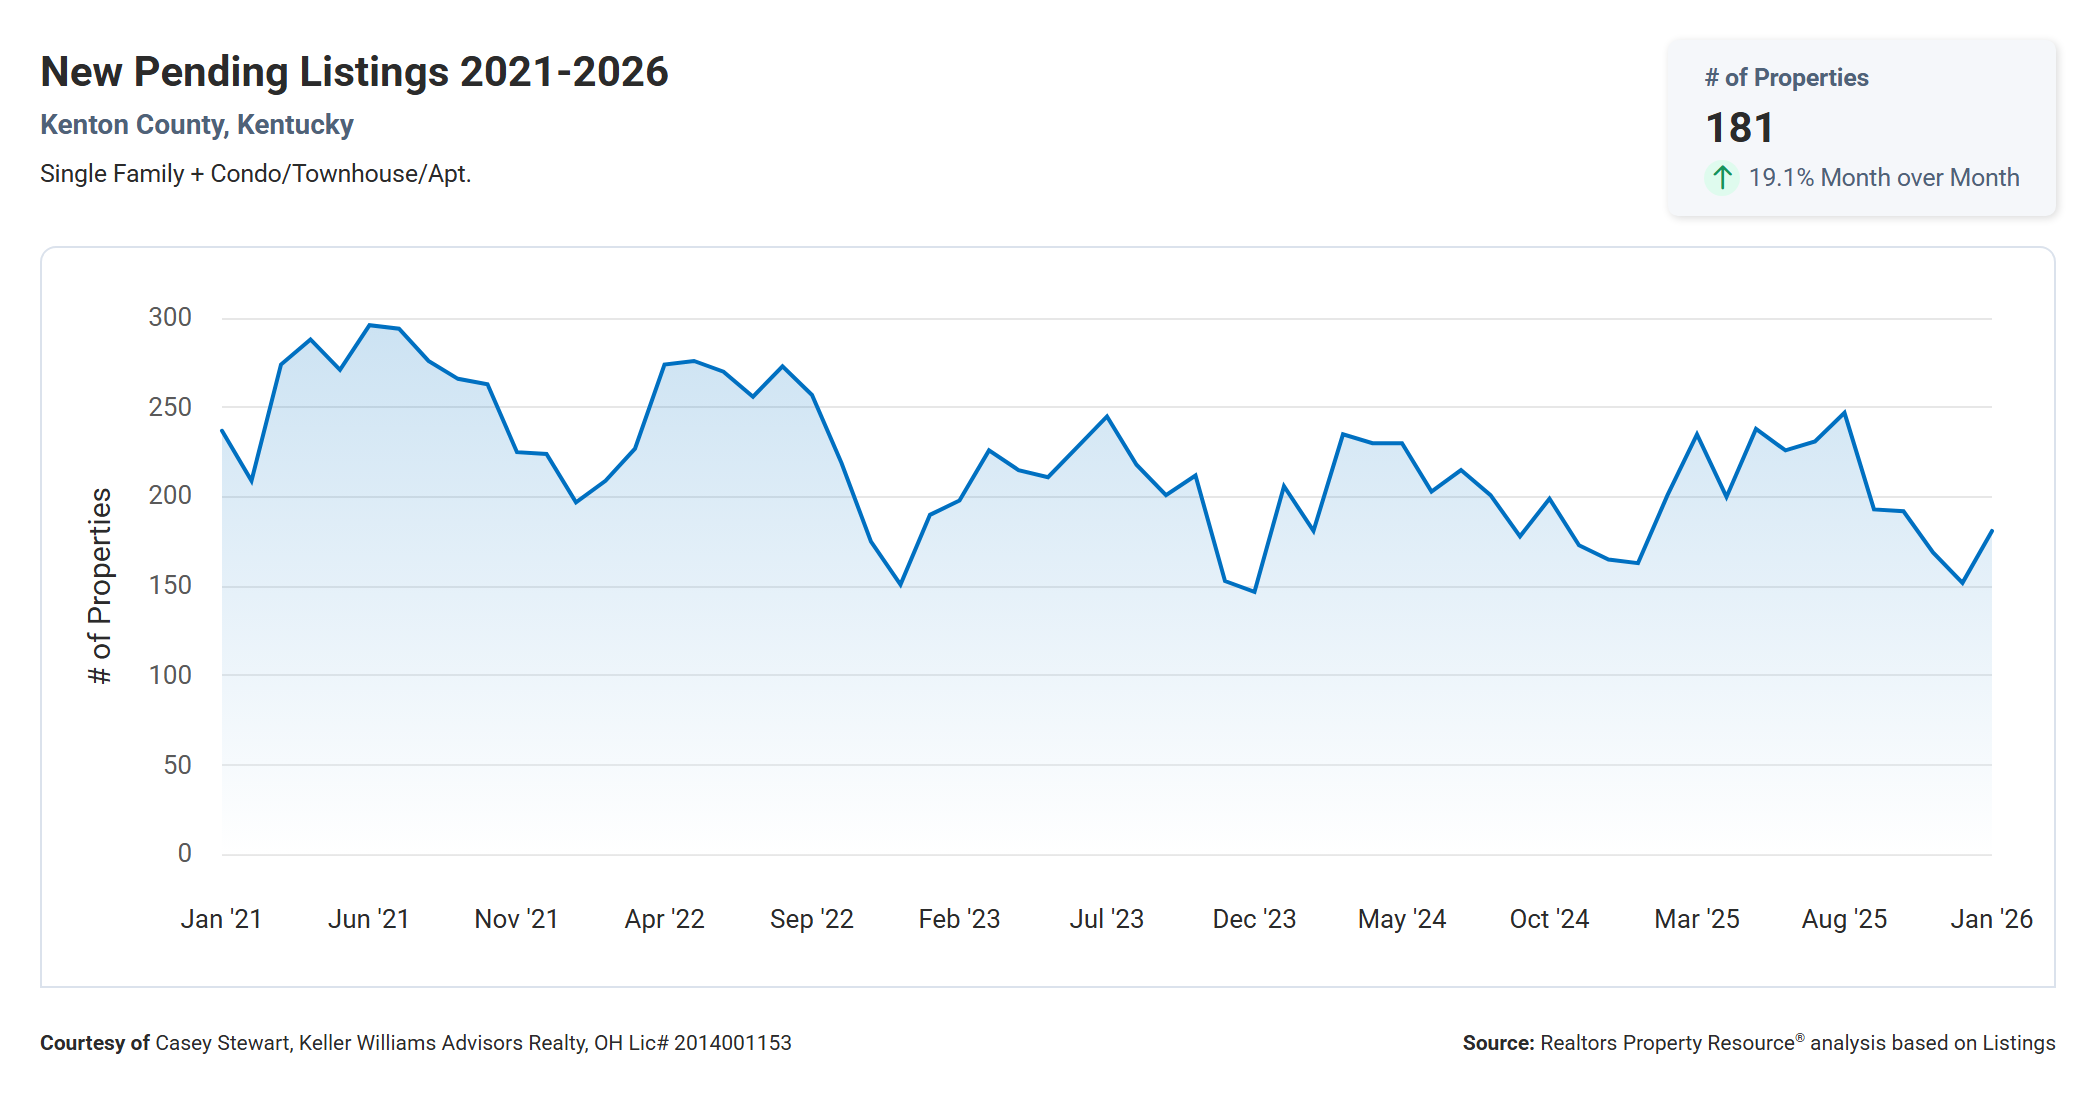
You can see in the charts above that these seasonal trends seem to be true throughout greater Cincinnati (each one pulled data from a different county), but keep in mind that this can vary on a micro level: urban, suburban, and rural markets all function a little differently, which is why it’s so important to review your specific situation with a great agent. Your price range, school district, and percentage of investors to owner-occupants can also affect market activity and timing, not to mention national factors such as mortgage rates and economic or political uncertainty.

My personal feeling is that the best time to sell your home is when you’re ready to sell: when you’ve made all the improvements you are willing and able to make, when you’re financially and emotionally ready for the change, and when you have a solid plan. The same concept applies to buyers! If you are financially prepared to buy a home, and homes in that price range align with your goals, it’s time to start looking.

“Ninety percent of all millionaires become so through owning real estate. More money has been made in real estate than in all industrial investments combined. The wise young man or wage earner of today invests his money in real estate.” - Andrew Carnegie

Your Buyer Agent Needs You to Commit

It’s really happening: just as clients who are selling their homes with an agent need to sign a contract, buyers are finally being asked to do so as well when seeking the services of a licensed agent. In fact, there are now regulations in place through the National Association of REALTORS® (NAR) and laws in many states requiring that any agent showing a property to a buyer have a written agreement in place beforehand. These agreements can take many forms, but this handy infographic provides a solid overview.

Buyer representation agreements, aka buyer broker agreements, are contracts between a real estate broker and a buyer in which the brokerage agrees to work on behalf of the buyer (both through advice and assistance with identifying potential homes and securing access rights to them), and the buyer agrees to ensure that the broker gets paid a commission for their services. If this concept sounds foreign to you, you’re not alone! Prior to a legal settlement that went into effect in 2024, most agents would work informally with buyers until they reached the point of writing an offer on a property — and even then, they would usually only commit to working with the agent for that transaction. If you’re wondering whether that led to agents showing many properties to many different people without any form of compensation…yes, that was definitely happening.

But agents sometimes not getting paid for their work wasn’t the root of the lawsuit and eventual settlement; on the contrary, it was the question of who was paying the buyer side commission and how that information was disclosed to all parties. (There were also claims that commission rates were artificially driving up home prices across the nation, but since the average commission rate actually decreased over the same amount of time, that was clearly incorrect). Before the settlement in 2024, the commission that sellers paid to their listing broker was customarily split with the buyer’s broker, and the exact amount of the split was advertised privately between brokers in the MLS. Some sellers felt that they were paying more than necessary since their commission was being used to compensate the agent representing the buyer, and buyers had no idea how much their agent would be paid until closing.

There were several scenarios in the old model that had the potential to harm consumers, such as agents potentially not showing listings that were offering low compensation splits, or encouraging buyers to make offers on homes that had “bonus” commission amounts. I didn’t come across this very often in my area, but it’s not hard to see how that could happen. Luckily, under the new guidelines, the amount of commission being paid to each agent and by whom will be much more clear, and while sellers have so far been willing to pay the buyer agent commission on behalf of most of my clients, that topic is now outlined in the offer to purchase so there are no surprises. Brokers can no longer advertise the amount of commission a seller is willing to pay on behalf of a buyer on the MLS, which will hopefully put all listings on a level playing field with buyer agents.

Two important exceptions to the buyer broker agreement rule are 1) that a listing agent MAY show their own listing to a buyer with whom they do not have a contract and 2) no contracts are needed for buyers attending an open house even if it is hosted by an agent other than the listing agent. In other words, if you’re a buyer who isn’t yet represented by an agent, you can schedule a showing directly with the listing agent or attend an open house. This can be very helpful for evaluating agents and viewing homes before you’re ready to commit, although some agents fear that it will lead to an increase in dual agency (where one broker or agent represents both parties in a transaction). There will always be bad actors who try to find a way around the rules, but the general hope is that having open and honest discussions about commission, and about commitment between client and agent, will lead to a higher standard of service for consumers.